EasyJet Agrees to a Massive $7.7 Billion Takeover by Apollo
EasyJet Agrees to a $7.7 Billion Takeover by Apollo
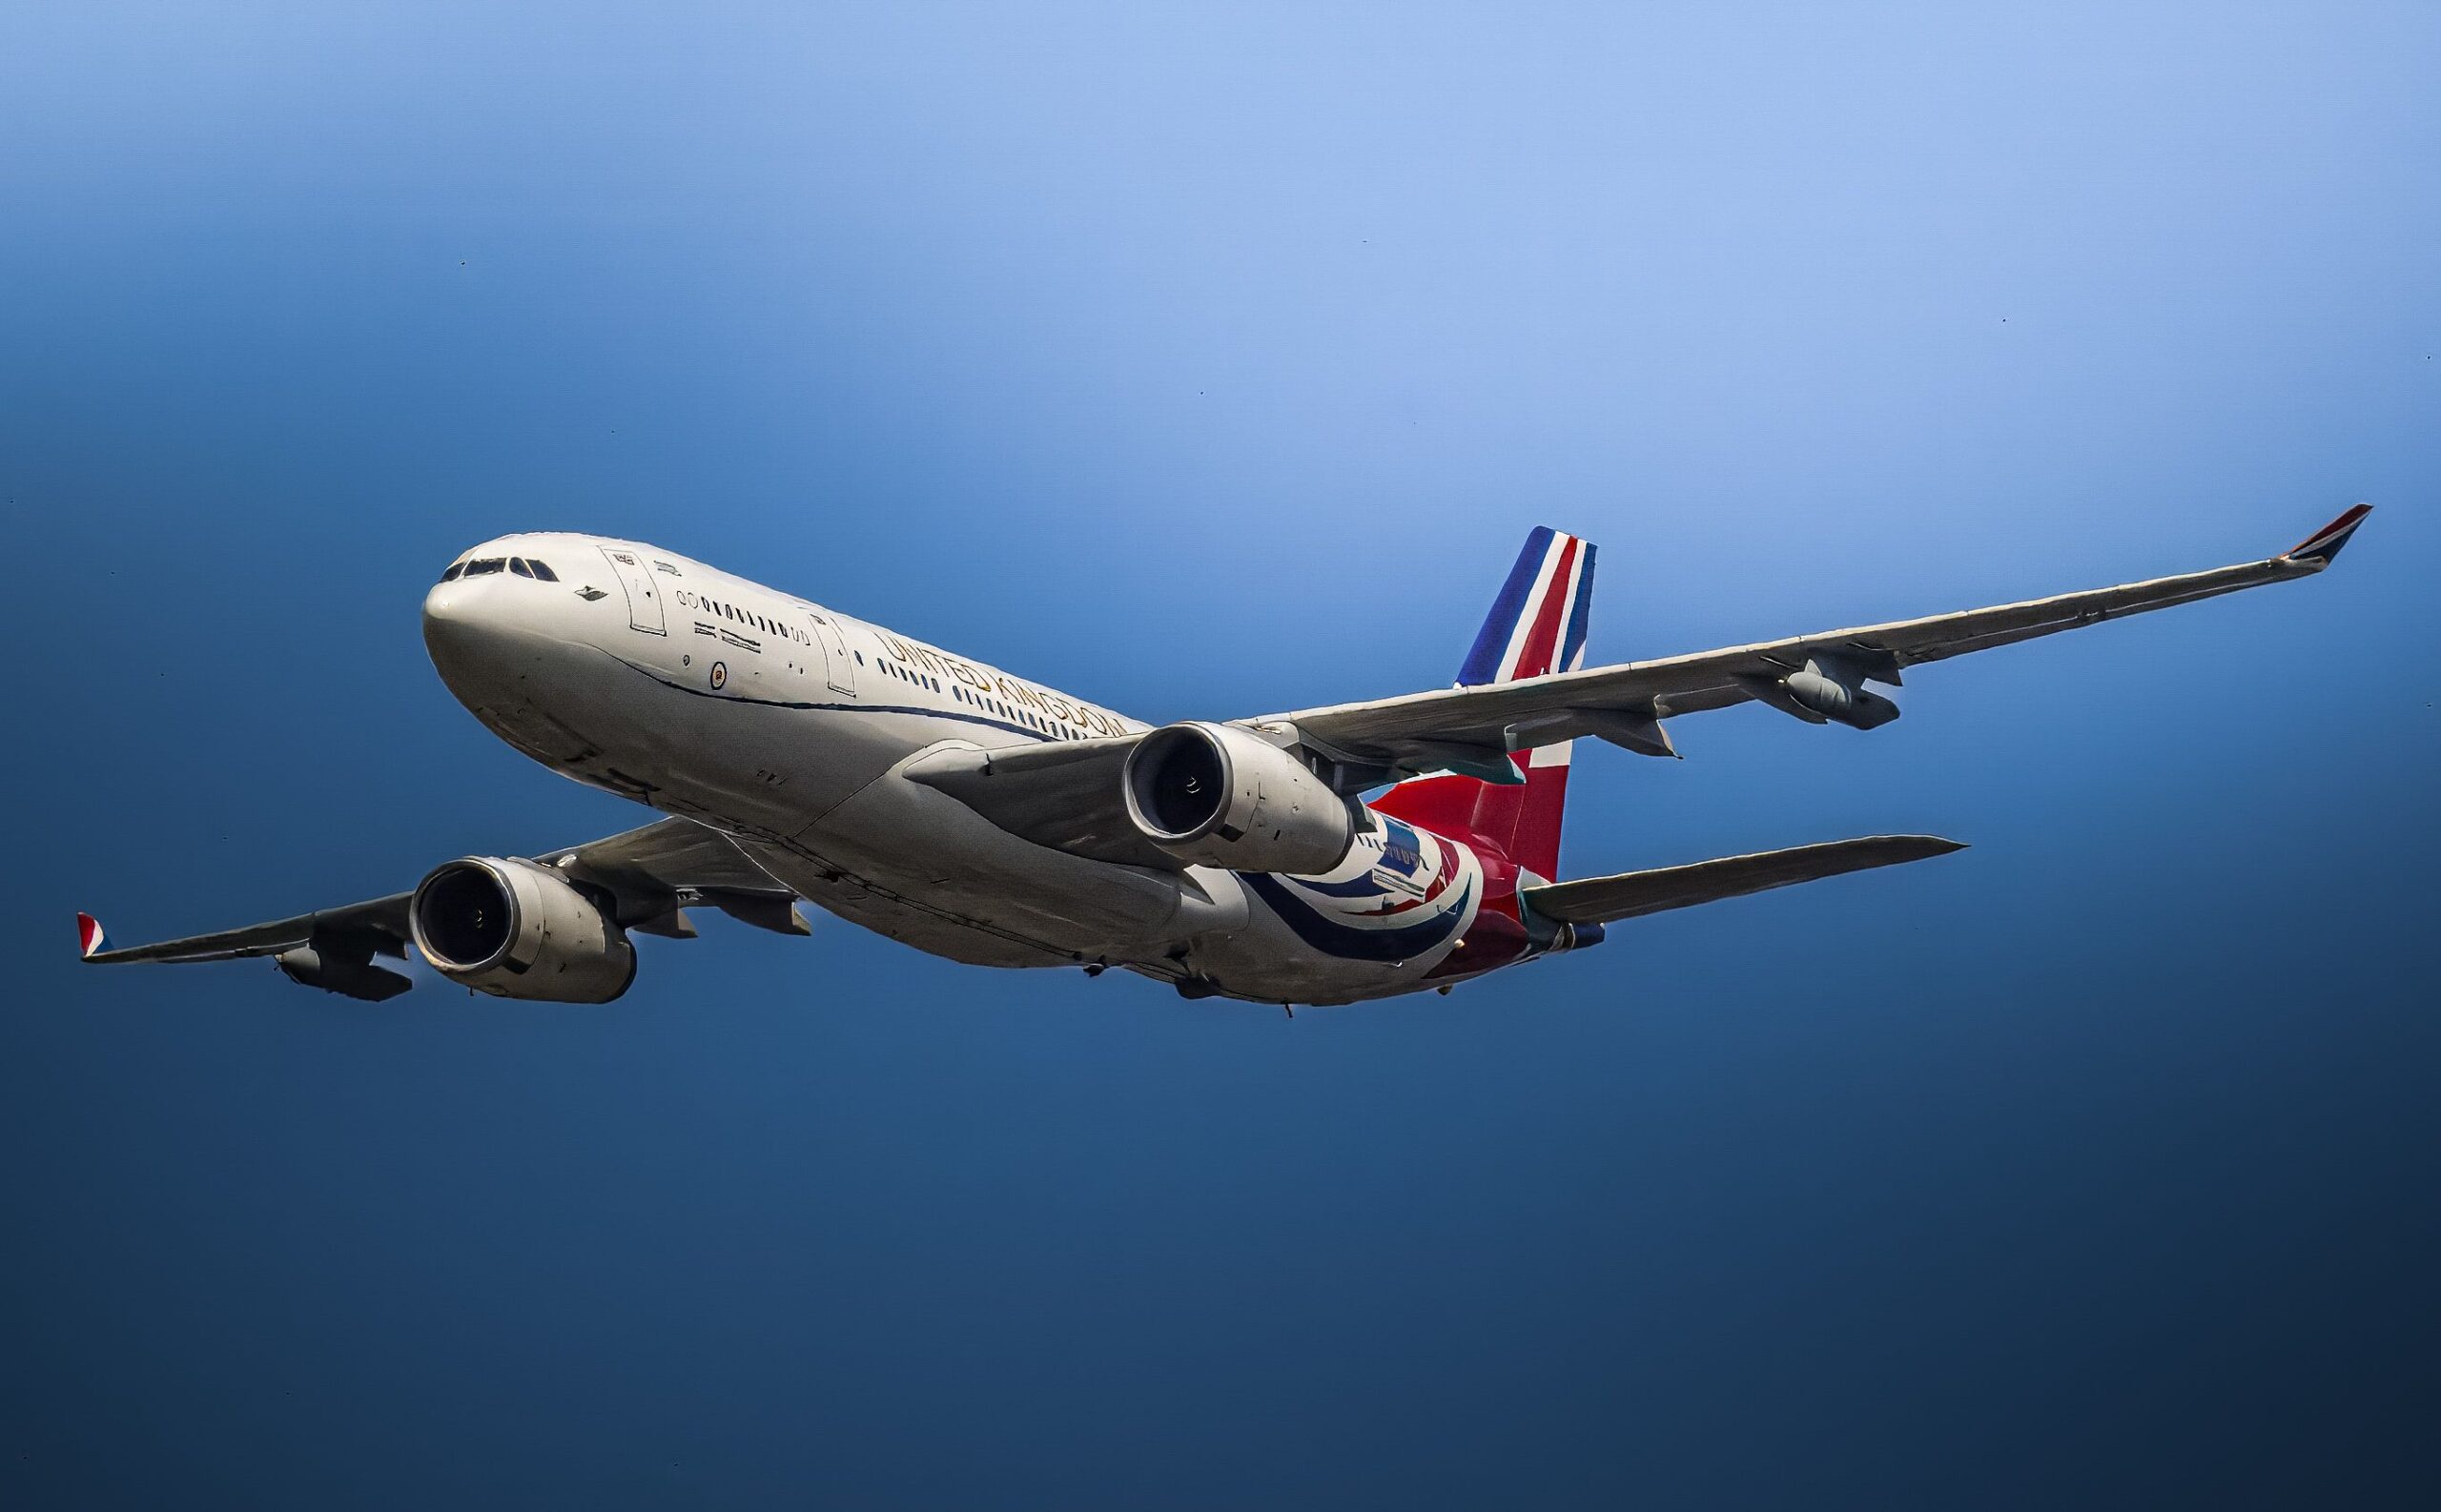
British budget airline easyJet has agreed to a massive takeover deal worth approximately $7.7 billion with U.S. investment firm Apollo Global Management. The agreement marks a major development for the European aviation industry and brings an intense bidding battle for the airline closer to an end. Apollo’s offer values easyJet at around £5.7 billion and represents a significant premium for shareholders compared with the airline’s share price before takeover interest emerged.
The easyJet takeover comes after weeks of growing interest from private equity investors. Before Apollo entered the race, U.S. investment firm Castlelake had been pursuing the airline and had already made several proposals. However, Apollo eventually came forward with a higher offer of £7.15 per share, prompting easyJet’s board to support Apollo’s proposal instead.
As a result, the easyJet takeover has become one of the most closely watched deals in the European airline sector. The transaction could change the ownership structure of one of Europe’s best-known low-cost carriers while giving Apollo greater control over the company’s future strategy.
Apollo Wins the Takeover Battle
The deal with Apollo followed a competitive process involving another major private equity firm, Castlelake. Castlelake had increased its proposal several times before reaching an agreement in principle with easyJet at £6.90 per share. However, Apollo later submitted a more attractive proposal of £7.15 per share. EasyJet’s board subsequently decided that Apollo’s offer provided a better outcome for shareholders.
The latest Apollo proposal represents an approximately 81% premium to easyJet’s share price before news of Castlelake’s interest became public. Therefore, shareholders are being offered a substantial incentive to support the transaction. The agreement also gives eligible shareholders the option of receiving cash or, under certain arrangements, rolling their investment into the company that will own easyJet after the transaction.
The easyJet takeover is particularly significant because the airline has been listed on the London Stock Exchange for more than two decades. If completed, the transaction would take easyJet into private ownership and bring an important chapter in its public-market history to a close.
Why Apollo Wants to Buy easyJet
Apollo appears to see significant long-term potential in easyJet despite the challenges currently facing the airline industry. The carrier has an extensive European network, a large fleet and valuable airport slots. It also has a growing holidays business that provides another source of revenue beyond traditional airline tickets.
In addition, Apollo has indicated that it wants to support easyJet’s existing strategy rather than simply change the company’s basic business model. The investment firm has expressed support for fleet modernization, improvements in ancillary services, stronger loyalty offerings and further expansion of easyJet Holidays.
This strategy could be important because airlines have traditionally operated with relatively thin margins and remain exposed to fuel prices, currency movements, economic conditions and geopolitical events. Private ownership could give easyJet more flexibility to make long-term investments without facing the same short-term pressure from public-market investors.
Moreover, Apollo could provide additional financial resources for aircraft investment, technology upgrades and expansion. The investment firm may also look for ways to improve the airline’s revenue generation while protecting its position as a major low-cost carrier.
easyJet Faces a Challenging Aviation Market
The easyJet takeover comes at a difficult time for the aviation industry. Airlines across Europe have faced pressure from high fuel costs, changing travel demand and geopolitical uncertainty. Recent conflict in the Middle East has also affected fuel prices and travel patterns, creating additional challenges for carriers. easyJet had previously warned that these factors were affecting its financial performance.
Higher fuel prices can have a major impact on an airline because fuel is one of its largest operating expenses. When prices rise quickly, airlines may find it difficult to pass the full increase on to customers without affecting demand.
At the same time, passengers have become increasingly sensitive to ticket prices. Low-cost airlines such as this compete heavily on affordability, meaning that increasing fares too aggressively could push customers toward competitors.
Nevertheless, easyJet has several strengths that make it attractive to investors. Its network covers a large number of European destinations, while its presence at important airports gives it access to valuable takeoff and landing slots. The airline also has a recognizable brand and a significant customer base.
What the Deal Means for easyJet Passengers
For passengers, the immediate impact of the easyJet takeover may be limited. The airline is expected to continue operating under the easyJet brand, while its existing network and customer services remain central to the business.
However, Apollo’s ownership could eventually lead to changes in the way the airline generates revenue. One area that may receive greater attention is premium services and additional passenger products. Industry reports suggest that Apollo could explore ways to make the airline more attractive to higher-paying customers while continuing to maintain its low-cost foundation.
For example, the company could increase its focus on extra-legroom seats, upgraded services, loyalty programs, business travel options and other paid extras. Such services can provide airlines with additional revenue without requiring a major increase in ticket prices.
At the same time, Apollo is expected to examine easyJet Holidays, which has become an increasingly important part of the company’s business. Package holidays can generate different revenue patterns from individual airline tickets and could provide a valuable growth opportunity.
Impact on easyJet Employees
Employees will also be watching the easyJet takeover closely. Private equity ownership often leads to questions about costs, efficiency and future employment levels. However, Apollo has indicated that it recognizes the importance of easyJet’s employees and intends to retain key staff. Reports have also said that Apollo plans to keep the airline’s UK headquarters and has pledged no job cuts during the first year following the transaction.
That could provide some short-term reassurance for workers. Nevertheless, the longer-term direction of the business will depend on how Apollo implements its investment strategy.
If the new owners focus heavily on expansion, employees could benefit from increased investment and new opportunities. On the other hand, if Apollo decides to reduce costs or reorganize parts of the company in the future, there could be further changes.
For now, the focus is expected to remain on completing the transaction and ensuring that easyJet continues to operate smoothly during the ownership transition.
Founder Supports the Apollo Deal
EasyJet founder Sir Stelios Haji-Ioannou and his family have also played an important role in the takeover process. The family owns approximately 15% of the airline and supports Apollo’s proposal. Rather than simply selling the entire holding for cash, the family plans to roll its stake into the new ownership structure.
That decision is significant because it shows that the founder’s family could continue to have an economic interest in easyJet after the company leaves the public markets.
The involvement of the founding family may also provide Apollo with additional confidence as it moves forward with the transaction. Keeping an existing major shareholder involved could help maintain continuity while the airline moves into its next stage.
Regulatory Approval Remains Important
Although the easyJet takeover agreement represents a major step forward, the transaction still faces regulatory and other conditions before it can be fully completed. One important issue is European airline ownership rules.
Airlines operating certain intra-European services must meet ownership and control requirements designed to preserve their operating rights. Because Apollo is a U.S.-based investment firm, the transaction has been structured to address these requirements. The proposed ownership arrangement includes mechanisms intended to ensure that easyJet continues to comply with applicable European rules.
Therefore, investors will continue to monitor regulatory developments closely. Approval from the relevant authorities will be an important part of the process before the transaction can officially close.
What Happens Next for easyJet?
The next stage will focus on completing the formal transaction process and satisfying the required conditions. EasyJet’s board has backed Apollo’s proposal, giving the deal strong support from the company’s leadership.
The withdrawal of Castlelake from the bidding process has also reduced immediate competition. However, the history of the negotiations shows how quickly the situation can change when private equity firms compete for an attractive target. Castlelake had previously made several proposals before Apollo entered the process with a higher offer.
For Apollo, the challenge now moves from winning the bidding battle to creating long-term value. Buying an airline for $7.7 billion is only the beginning. The investment firm will need to manage fuel costs, aircraft investments, passenger demand and competition while also finding new ways to increase revenue.
Consequently, the success of the easyJet takeover will ultimately depend on whether Apollo can improve the airline’s financial performance while maintaining the qualities that have made the brand successful.
A Major New Chapter for European Aviation
The easyJet takeover represents more than a change in ownership. It reflects a broader trend in which private equity firms are showing strong interest in established companies whose share prices or valuations may not fully reflect their long-term potential.
EasyJet has faced several difficult years, including the disruption caused by the pandemic, higher operating costs and geopolitical uncertainty. Yet the airline continues to possess valuable assets, including a large European network, a recognized brand, airport slots and a growing holidays operation.
Apollo is betting that these strengths can be developed further through private ownership and additional investment.
For easyJet, the transaction could therefore mark the beginning of a new phase. The airline that once helped reshape European air travel through its low-cost model may now enter an era where private equity ownership drives its next stage of growth.
Overall, the $7.7 billion Apollo deal is a major event for easyJet, its shareholders, employees and passengers. While there are still important steps before the transaction is fully completed, Apollo’s agreement represents a decisive moment in the airline’s future. The coming years will show whether the new owners can unlock the value they see in easyJet while preserving the strong European network and recognizable low-cost model that made the airline a major name in aviation.
China Exports Growth Beats Estimates As AI-Powered Shipments Drive July Trade